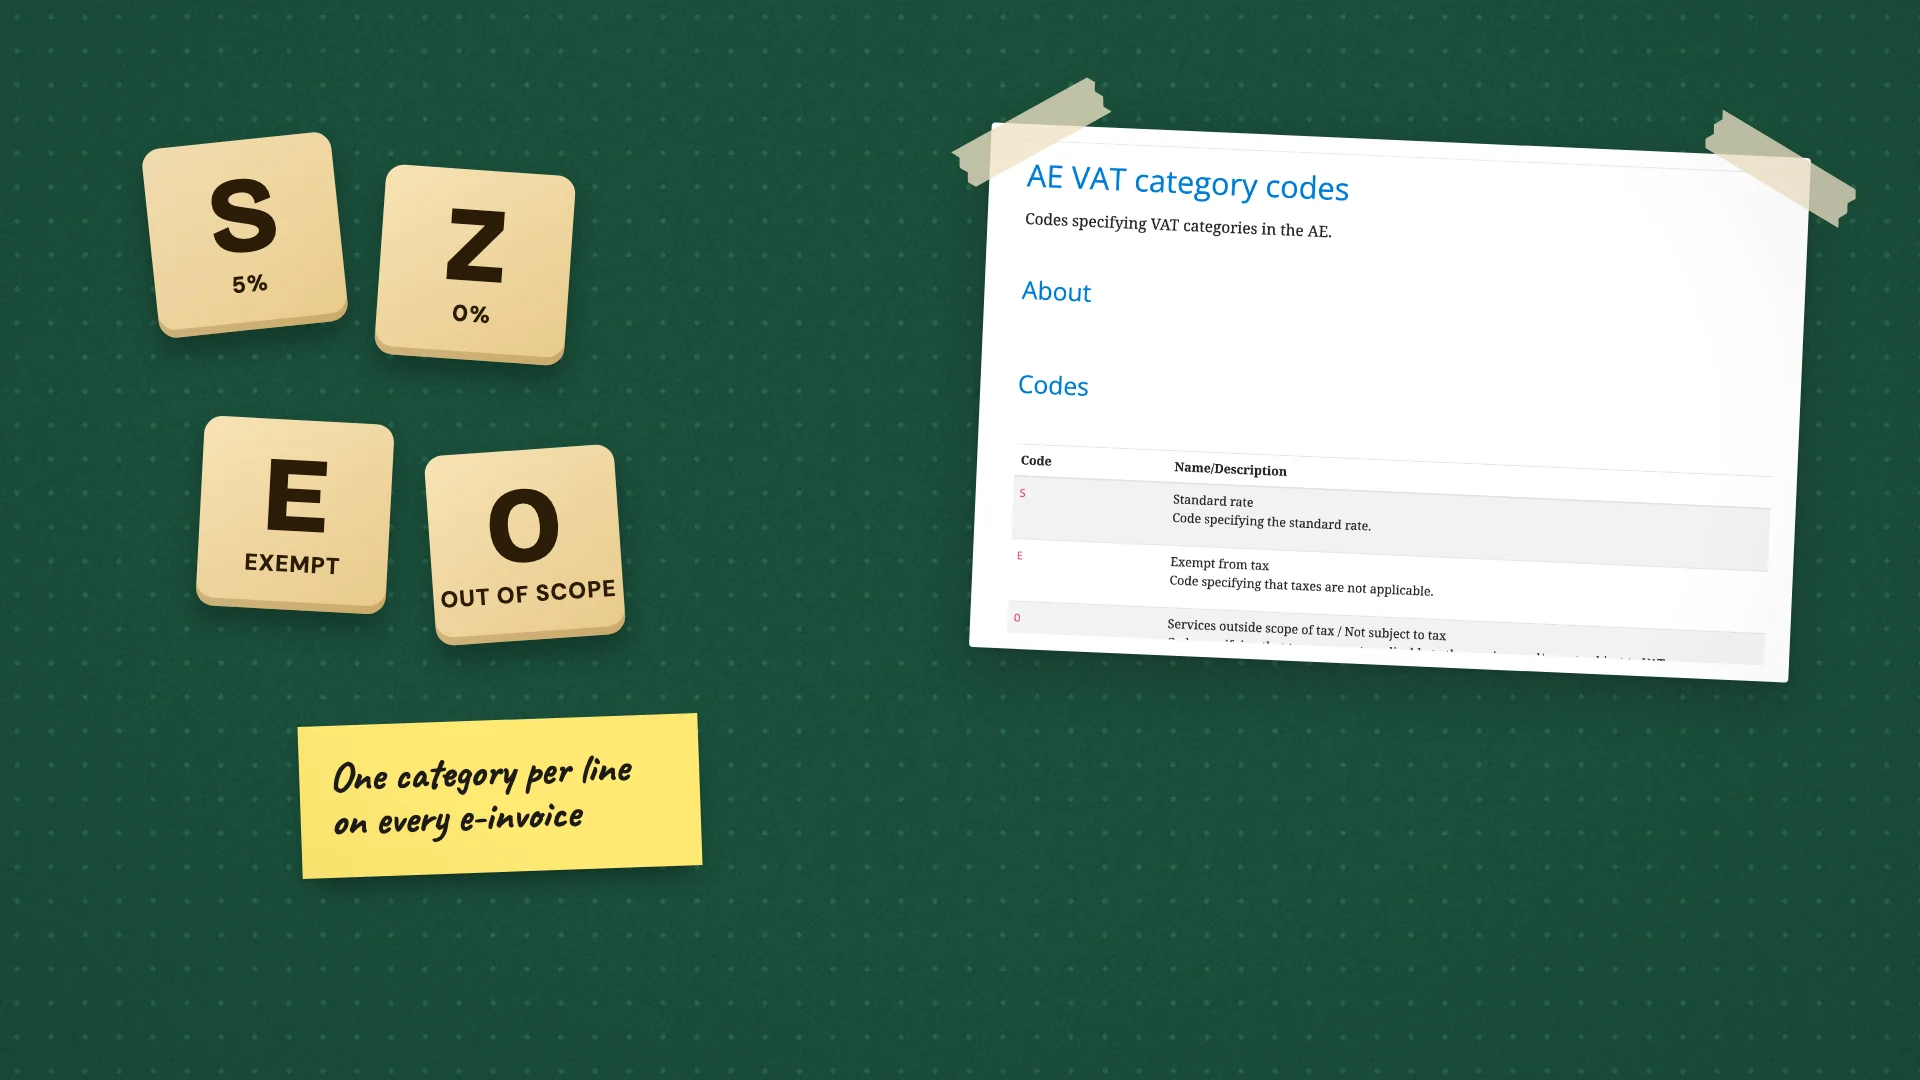
Most agency invoices today show one VAT rate for the whole document. Under e-invoicing each line has a category: standard rated, zero rated, exempt, out of scope, or reverse charge for certain domestic goods. A wrong choice is no longer hidden inside a total.
The four treatments
- Standard rated (S): 5% VAT. The default for agency services supplied in the UAE.
- Zero rated (Z): taxable, but at 0%. You still recover the VAT on your costs.
- Exempt (E): not taxable, and you cannot recover the VAT on the related costs.
- Outside the scope (O): neither taxable nor exempt, outside the VAT system altogether.
Why agency work is almost never exempt
Article 46 of the VAT Decree-Law lists only four exempt categories: certain financial services, residential buildings that are not zero-rated, bare land and local passenger transport. Creative, media, PR and production services fall in none of them. Treating a service as exempt when it is not undercharges VAT and also blocks your input VAT recovery.
When agency work is zero-rated
Article 45 zero-rates 14 kinds of supply. The one that matters for agencies is the export of services under Article 31 of the Executive Regulation: the client has no residence in the UAE and is outside the UAE when the work is done, the work is not connected with UAE property or goods in the UAE, and it is not a service the law treats as performed here. Services performed outside the UAE can qualify too. If someone in the UAE, such as the client's local staff, will receive the service and could not recover the VAT in full, the zero rate does not apply.
What is outside the scope
- Disbursements: costs paid as the client's agent and passed on at exact cost.
- The transfer of a whole business, as a going concern, to a taxable person.
- Fees from government bodies acting in a sovereign capacity and not competing with the private sector.
- Work done by employees, which is not a business activity.
- Supplies whose place of supply is outside the UAE.
Designated zones are not tax-free for services
A client established in a designated zone is a UAE resident, and services supplied in a designated zone are treated as supplied in the UAE. Only qualifying goods get special treatment. On 2 October 2026 the FTA published a new guide, TAXP010, on designated zones for corporate tax, VAT and excise.
How e-invoices label each line
- Each line carries its category code: S, Z, E, O, or AE for the domestic reverse charge.
- Exempt lines must carry an exemption reason code, such as DL8.46.1 for financial services. Standard-rated lines must not carry one.
- Out-of-scope lines carry no rate, and no rule requires a reason.
- Zero-rated supplies need a full tax invoice. The relief for wholly zero-rated supplies does not apply to e-invoices.
A quick guide for agency invoices
- A retainer for a Dubai brand: standard rated, 5%.
- Campaign strategy for a London client with no UAE presence, done while they are abroad: usually zero rated, if the export tests are met and documented.
- An event or shoot in the UAE for a foreign client: check the place of supply rules for cultural, artistic and similar services before zero-rating.
- Media bought in the client's name and passed on at cost: outside the scope as a disbursement.
- Media bought in your name and recharged: follows your main service, usually 5%.
The VAT calculator on this site works out 5% VAT on any amount, inclusive or exclusive, for the standard-rated lines.